Dated: 03/20/2020
Views: 9
Arin Williams
As a career photojournalist and business expert, I bring a uniquely powerful skillset to the table. I’m an expert in digital marketing and know how to create content that moves people — and propertie….
Dated: 03/20/2020
Views: 9
As a career photojournalist and business expert, I bring a uniquely powerful skillset to the table. I’m an expert in digital marketing and know how to create content that moves people — and propertie….
Here’s the latest from Dave Ramsey:
Debt

By now, you know exactly how we feel about credit scores (hint: they’re bogus). But one thing you still need to pay attention to is your credit report. Even if you’re debt-free and don’t care what big banks and lenders think of you, you can’t just ignore your credit report. You still need to check it for errors or signs of fraud at least once a year.
But sifting through these things can be pretty confusing, especially if you don’t know how to read your credit report or what kind of red flags to look for. We know it can be a lot to take in. But don’t worry! We’ve done the heavy lifting so you don’t have to. Ready, set, let’s walk through everything you need to know about how to read your credit report.
A credit report is kind of like a report card for your credit history. It can be used by potential lenders to determine your “risk,” which is basically just how likely you are to pay your monthly payments on time. A credit report all about you can tell them:
The date you opened any credit accounts or took out any loans

Take control of your money with a FREE trial of a Financial Peace Membership.
The current balance on each account
Your payment history
The credit limits and total loan amounts
Any bankruptcies or tax liens
Your identifying information (name, address, Social Security number)
A credit bureau or credit-reporting company like Equifax, Experian or TransUnion will provide your information to whatever company may be considering giving a loan or credit account. These bureaus all operate independently, so their reports on you may contain slightly different information depending on the credit-reporting company they used.
You’re allowed one free copy of your credit report every year from each of the major credit-reporting agencies we just talked about. But the reports aren’t automatically mailed to you—you have to ask for them! And since each agency keeps different details on file, it’s worth checking with all three. If you play your cards right, you can even stagger them so you’re getting a free report nearly every quarter.
Now that you know how to get your credit report, we’ll walk you through the four major areas you need to check for any red flags. These could help you spot potential identity theft situations, so listen up!
This section has any personal information that could be used to identify you, including:
Name
Address
Social Security number
Date of birth
Phone number
Red Flags: Everything in this section needs to refer to you and not someone else who happens to share your name, Mr. Jones. And while you’re at it, go ahead and double-check the Social Security number just in case, too.
Make sure all the addresses listed are places you’ve actually lived. If you’ve never been to Waxahachie, Texas, but the report says you lived there for seven years, you might want to follow up on that. We’ll share later what steps to follow if you do find errors in your report.
The bulk of the report is in this section. Your credit history includes:
Open and paid credit accounts, like credit cards, mortgages and loans
Accounts shared with someone else
Total loan amounts
Remaining loan balances
Late payments
Accounts that have been sent to collections
Red Flags: Read and reread this section to make sure everything listed is right. Got it? Okay. Now check again. Seriously. Look for accounts that were opened that sound unfamiliar, and check for payments being noted as late when they actually weren’t.
If you’ve closed a credit card account, confirm it’s showing up as closed on your credit report. Also, make absolutely sure no lines of credit have been opened in your name without your consent—that’s a huge red flag and might mean you’re at risk of identity theft.
You want this part to be blank. The financial activity listed here—like bankruptcy, tax liens and judgments—is taken from public records, and some things can stay on your credit report for upwards of 7–10 years.
Red Flags: It’s pretty rare to find an error in this part of the report, but it’s worth scanning anyway. Mistakes in this section should be cleared up ASAP.
Here you’ll see detailed listings of every business that has requested your credit report. There are two types of credit inquiries: soft and hard. Soft inquiries are just from companies wanting to send you promotional materials or current creditors checking your account. Hard inquiries are made when you actually apply for a credit card, loan or mortgage.
Red Flags: Hard inquiries cause your credit score to drop a few points, so be sure you’ve truly given your permission for a hard inquiry to your credit. These should disappear from your report after about two years.
An open account is any line of credit you’ve opened and never officially closed. You know, like that paid-off department store credit card you forgot to call about and cancel. Even if you haven’t used a credit card for a few years, it will still show up as an open account on your credit report until you contact the company to close the account. So, stop having cold feet and just go ahead and close it for good.
University of Credit Reporting? Nope. The “U” means “unclassified,” or that the account hadn’t been updated at the time the report was pulled. It’s one of many status codes that can appear next to an account on your credit report. Codes like this usually indicate a problem with the account, like it being past due or sent to collections.
You might also see a “U” if the account is new and you haven’t made any payments on it yet. It doesn’t have a negative impact on your credit score and isn’t anything to really worry about.
Most people can’t legally use your personal information to access your credit report. However, there are several types of organizations that are allowed to pull your credit: banks, creditors, lenders, insurance companies, potential landlords, collections agencies, potential employers and the government.
The laws about who can access your credit score are different from state to state. If you’re worried at all, do some research and find out what the law is where you live.
If you got a free credit report, don’t be surprised when it doesn’t include your credit score. To see that, you’ll have to use a free web service or pay for it through MyFico.com or a credit bureau.
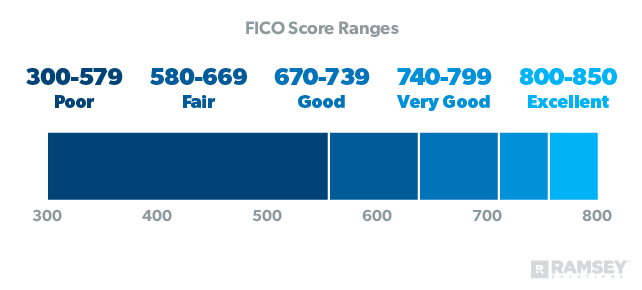
But keep in mind, when it all comes down to it, a credit score is really just an “I love debt” score. That’s right, a “good score” simply shows how well you’ve played the debt game. It doesn’t reflect your actual net worth or the amount of money you have in the bank. In other words, it’s nothing to be proud of. The only way to keep your stellar credit score is to live in debt and stay there. No thanks!
It is possible to live life without a credit score, which is exactly what Dave recommends. But that doesn’t mean you should trash your credit to lower it! Just start paying off your debt, close your credit accounts once they’re paid off, and don’t take on any new debt. If you’re following the Baby Steps, you should reach that indeterminable score within a few months to a few years. Remember: No credit is not the same as having a low credit score.
It depends. Like we said earlier, there are soft inquiries and hard inquiries. Soft inquiries happen all the time without you even knowing—a company might check your credit score if they’re planning on mailing you a promotional offer. These inquiries don’t affect your credit score at all.
But hard inquiries require your actual consent before they can happen. These impact your credit score and can’t legally be done without you knowing, so breathe easy. If you notice a hard inquiry you didn’t authorize, you’ll need to dispute it with the credit agency.
Any mistakes on your credit report need to be taken up with the agency that shows the error. Write a letter that lists each incorrect item you found and why you’re disputing it.
Let’s say you closed a credit card, but it still shows up as an open account on your credit report. Here’s what you need to do: Gather up documents and any evidence you might have to prove it’s a mistake. Then, send all of this by certified mail—and don’t forget a return receipt! The agency has only 30 days to respond, so you should see some movement pretty quickly.
Your credit report might seem complicated at first, but now that you know what to look for, hopefully it’s not so daunting. It’s never a bad idea to be proactive and make sure everything is correct. Staying on top of your credit report is a great way to guard yourself from identity theft, so make sure you’re protected!
Here’s the latest great post from The Penny Hoarder:
Some of the links in this post are from our sponsors. We provide you with accurate, reliable information. Learn more about how we make money and select our advertising partners.
Want to know a secret?
I’ve never had a professional massage. I totally get why they’re appealing, but they’re just not my jam.
Manicures, on the other hand? Heck, yeah. My tombstone will read, “How do my nails look?”
I’m not gonna lie, getting my nails done every two weeks or so costs a pretty penny (or 6,000, to be exact), but it’s the one luxury I budget for even if it means using cheap body wash or mascara.
The main reason I go to a salon to get my manicure done is because there’s no way I could do it at home. I’m basically the most uncoordinated person on the planet, so I’d end up with acrylic powder in my eye and nail shellac on the walls.
For all other spa-type treatments, though, I’m strictly a DIY gal.
Here are some of my favorite ways to indulge myself easily right in the comfort of my own home.
Not only will you not have to leave the comfort of home, but these ideas won’t cost you a fortune.
1. Everything you’ve heard about coconut oil is true. Skip the expensive body lotion and the deep conditioner and use this low-cost alternative instead.
Cost: An entire jar of coconut oil costs about $6 and will last for months.
2. Apply an avocado or egg mask to your hair at the beginning of your spa routine, then wrap your head in a warm towel. Let it work its magic for at least 20 minutes while you give yourself a lip scrub.
Cost: One egg will set you back 10 cents, and an avocado is between $1 and $1.50.
3. Korean sheet masks, cotton-based sheets that address various skin care issues, make your skin look amazing, but they can be awfully pricy. I picked up a handful at my local dollar store for a buck each and discovered they work just as well as the expensive brands. If you buy in bulk, you can save even more pennies.
Cost: Sheet masks can be found online or in dollar stores for as little as — you guessed it — $1.
4. Speaking of masks, if you use Lush cosmetics or know someone who does, hang onto those little black pots and bottles the products come in. You’ll score a free face mask when you turn in five clean empties. That’s a savings of at least $11.95!
Cost: The cost of the five products (To be fair, Lush products can be pretty pricy — but they smell so gooood.)
5. Clear up blemishes and reduce fine lines with a container of plain, generic-brand yogurt! Whether you use it alone or jazz it up with extras like a dash of honey or oatmeal, your pores will thank you.
Cost: A small container of plain yogurt can cost anywhere from 60 cents to $1.
 Heather Comparetto/The Penny Hoarder
6. After rinsing off the mask, I like to give myself a five-minute face massage. It’s surprisingly relaxing.
Cost: Totally free!
7. If you’ve got a few dollars a month to spare, sign up for a Sephora Play! subscription. You’ll get a box delivered right to your door filled with deluxe product samples and a bonus fragrance.
Cost: $10 per month
8. This homemade eucalyptus sugar scrub is both energizing and effective. You can make a batch to slough off dry, dead skin, leaving behind a tingly clean that smells luxurious.
Cost: Less than $1 worth of sugar, coconut oil and salt, plus around $13 for eucalyptus essential oil.
9. For a change of pace, I like to mix things up and exfoliate my skin with this three-ingredient coffee body scrub that you can make with the (free!) used coffee grounds left over from your morning brew. It reportedly also reduces the appearance of cellulite. (Don’t tell me if that’s just an old wives’ tale — I don’t want to know.)
Cost: Free, if you’re a coffee drinker.
10. Sometimes my skin just isn’t up for a harsh scrub down. That’s when I whip together this gentle scrub that rinses off easily with warm water. (I’ve tried it without wheat germ, and it still works great.)
Cost: About $10 for the oat bran, $7 for the essential oil and $6 for the almond oil – and you can use all of these for other purposes too.
11. If you plan to shave during your spa time, try dry brushing first to prevent ingrown hairs and razor-burn bumps.
Cost: A good dry brush costs around $7.50
12. If I’m going to sport beautiful nails, the rest of my hand better keep up appearances, too. This lemon-sugar hand scrub is so easy to make and smells amazing. After you rinse it off, slather on some hand lotion and take a minute to admire your, er, handiwork.
Cost: A lemon costs about 50 cents, and you probably already have sugar and oil in your pantry.
13. Do you know why every spa scene in a movie or on TV depicts someone with cucumber slices on their eyes? Because they work! You can use the leftovers for cucumber-infused water to really amp up that luxe “I’m in a spa” feeling.
Cost: About $1 for a cucumber.
 Heather Comparetto/The Penny Hoarder
14. Treat your feet to a nice soak with whatever gentle bath wash you have on hand. Follow it up with a homemade foot scrub. Simply stir one part coconut oil into two parts sugar and scent with a few drops of essential oil. A dash of lemon juice adds extra oomph. To kick (ha!) things up a notch, slather on some lotion and cover your tootsies with thick socks while the moisturizer works its magic.
Cost: Peppermint essential oil costs about $9, or you can just use the eucalyptus oil you bought earlier. The rest of the ingredients are likely in your pantry.
 Heather Comparetto/The Penny Hoarder
While planning your day of indulgence, don’t forget to design your own relaxation grotto. Give your bathroom a deep clean and then:
1. Splurge on a soft, thick towel.
2. Pick up some pretty containers from the dollar store to hold all the scrubs and potions you make.
3. Scour thrift shops for a fluffy bathrobe to wear while relaxing.
4. Get some inexpensive candles to create ambience during bath time — or make your own.
5. Set a plant or vase of flowers in the bathroom, because greenery makes everything better.
6. Cover your bathroom window with frosted contact paper to diffuse bright sunlight that might harsh your mellow.
7. Put a few sprigs of eucalyptus on the corner of the bathtub to create a clean, refreshing scent when you run the hot water.
8. Buy a bathtub overflow drain cover so you can fill the tub extra deep and soak all the way up to your chin.
9. Queue up this chill Spotify playlist.
10. Use the cucumber you bought for your eyes to make some cucumber-infused water to sip as you spa.
Want even more DIY spa ideas? Check out how to make your own sea salt spray, body lotion and more.
Lisa McGreevy is a former staff writer at The Penny Hoarder.
Here’s the latest great post from The Penny Hoarder:
The IRS has released a feature on its website that will get you your coronavirus relief check faster if you aren’t required to file a tax return.
The Non-filers Enter Payment Info Here feature debuted on the IRS website on Friday, April 10. For several weeks, the IRS had urged people who don’t file taxes or receive Social Security benefits to file a simple tax return to speed up the payment process.
Here’s all of our coverage of the coronavirus outbreak, which we will be updating every day.
Using the free new feature, you can get your stimulus payment without filing a tax return by providing your:
You’ll also need to provide the name of each child you’re claiming as a dependent, their Social Security number or Adoption Taxpayer Identification Number, and their relationship to you and your spouse.
You’ll get an additional $500 for each child under 16 you claim on top of the $1,200 you’ll get if you’re single or $2,400 if you’re married.
You can use the tool if you aren’t required to file a tax return because your gross income for 2019 was below $12,200 if you’re single or $24,400 if you’re married.
If you receive Social Security benefits, you don’t need to enter your information; the IRS will use your benefits statement to process your payment.
However, if you get Supplemental Security Income or VA benefits but not Social Security, you should use the non-filers tool or submit a simple tax return.
If you’ve already filed a 2018 or 2019 tax return or you plan to do so, you should NOT use this feature.
Using the non-filer feature is probably a safe bet if you didn’t earn income in 2018 or 2019. But if you had some type of income, consider using a free tax filing program to determine whether you’re eligible for any tax credits first. You can prepare a draft return and then use the non-filer feature if you don’t find any you qualify for.
One credit you may have overlooked is the Earned Income Tax Credit. As of December 2019, about 25 million Americans with low or middle incomes qualified for the credit, which averaged $2,459. But about 21% of them missed out on that free money because they never claimed the credit.
Pro Tip
If you were eligible for the Earned Income Tax Credit in a past year, you can file a past return for as far back as 2016 to claim the credit.
But whether you use the non-filer tool or file a tax return, it’s important that you do so quickly to get your payment — and that you provide your bank account information. The IRS has already started depositing payments, and if you receive a paper check, you could add months to your wait time.
Robin Hartill is a CERTIFIED FINANCIAL PLANNER™ and a senior editor at The Penny Hoarder. She is the voice behind the Dear Penny personal finance advice column.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Nullam dictum felis eu pede mollis pretium. Integer tincidunt. Cras dapibus. Vivamus elementum semper nisi. Aenean vulputate eleifend tellus. Aenean leo ligula, porttitor eu, consequat vitae, eleifend ac, enim. Aliquam lorem ante, dapibus in, viverra quis, feugiat a, tellus.
Lorem ipsum dolor sit amet. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor. Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla suctus. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.
Lorem ipsum dolor sit amet, consectetur adipiscing elit. Morbi sagittis, sem quis lacinia faucibus, orci ipsum gravida tortor, vel interdum mi sapien ut justo. Nulla varius consequat magna, id molestie ipsum volutpat quis. Suspendisse consectetur fringilla luctus. Fusce id mi diam, non ornare orci. Pellentesque ipsum erat, facilisis ut venenatis eu, sodales vel dolor.